If you only watch one number this fall, watch the mortgage rate.
Last Thursday the average 30-year fixed rate hit 7.40%.
That is the seventh weekly increase in a row, and the highest reading since November 2023.
A year ago it was 6.30%.
I talk with buyers every week, and this is the number that comes up first.
The rate did not creep up.
It climbed past 7% two weeks ago for the first time in 19 months and kept going.
This Week's Numbers
These are the same numbers every Monday, so you can see the pattern build over time.
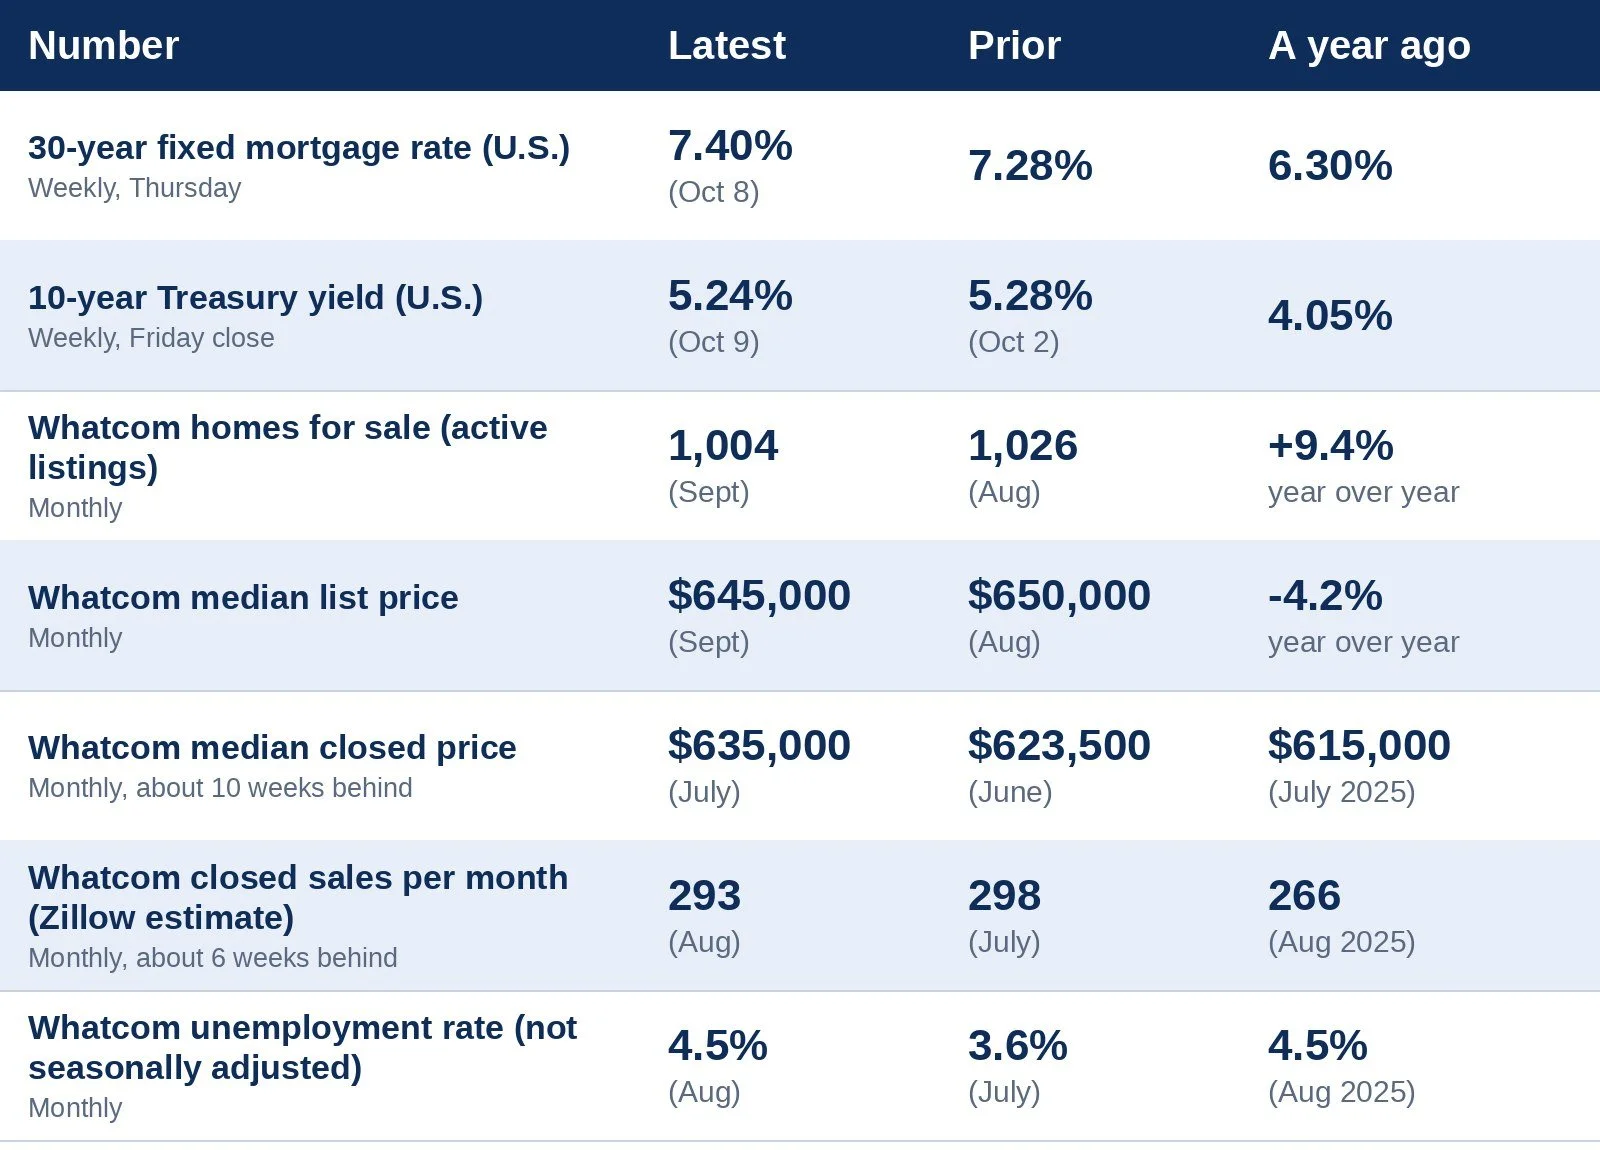
All property numbers cover single-family homes and condos/townhomes only (no multifamily, land or commercial).
Local numbers cover the Bellingham metro area, which is all of Whatcom County.
Listings and list price show what sellers are asking.
The two closed-sale rows show what homes actually sold for, with a lag.
What the Numbers Say
Rates. The 10-year Treasury yield sets the direction for mortgage rates, and it has been sitting around 5.2% to 5.3% all month.
It touched 5.31% on October 5 and ended Friday at 5.24%.
Mortgage rates follow it, so I would not count on relief until bond yields turn.
Inventory. Whatcom had 1,004 homes for sale in September, 9.4% more than a year ago.
The monthly count dipped slightly from August, but it is still well above last year.
Nationally, active listings are up 6.7% from a year ago, so Whatcom is running a bit hotter than the country on supply.
Price. The median list price in Whatcom was $645,000, down 4.2% from a year ago.
Asking prices have slipped each month since July.
Sellers are also cutting more: 19.7% of Whatcom listings carried a price cut in September, up from 16.2% in June.
Nationally the figure is 20.8%.
Closed sales tell a slower-moving story: the median closed price was $635,000 in July, up 3.3% from a year ago.
Asking prices are the early signal and closed prices confirm it, so I will watch both.
Jobs. Whatcom's unemployment rate jumped from 3.6% in July to 4.5% in August.
That was the biggest one-month increase in over two years, though it only matched where we were in August 2025.
Statewide, Washington was at 4.9% in August, but that figure is seasonally adjusted, so it is not a direct comparison.
How These Numbers Connect to Your Mortgage Rate
Mortgage lenders price home loans off the 10-year Treasury yield.
Investors who buy mortgage bonds compare them to Treasuries, so when the 10-year yield rises, mortgage rates follow.
Lenders then add a cushion on top, usually around two percentage points.
This week that gap was about 2.1 points (7.40% mortgage rate vs a 5.28% weekly average yield), so almost all of the move in your rate comes from the yield.
Over the last ten years that gap has averaged about 2 points, so the rise in your rate is coming from the bond market, not lender markups.
Jobs and inflation sit behind the yield.
Strong hiring and rising prices push the Fed toward raising rates and push yields up.
Weak hiring can pull yields down, but not always: the September jobs report was soft and rates still climbed because inflation worries and oil prices dominated.
Our local unemployment rate works differently.
It does not move mortgage rates, which are set nationally.
It tells us how confident and how able Whatcom buyers are.
A county that is shedding jobs gets fewer buyers and more price cuts, even before rates change.
So I watch the national numbers to see where your rate is going, and the local numbers to see how our buyers will handle it.
What This Means for Buyers
The math is the story.
On a $645,000 home with 20% down, the monthly principal and interest payment is about $3,573 at 7.40%.
At last year's 6.30% it would be about $3,194.
That is roughly $379 more each month for the same house.
The good news is that you have more choices and more room to negotiate than you did a year ago, and sellers are cutting prices.
If you are shopping, get a rate quote this week and again before you write an offer, and build a cushion into your budget.
What This Means for Sellers
More homes for sale, higher rates and more price cuts all point the same way.
Homes that are priced to where buyers can actually afford them still get attention.
Homes that start high are the ones piling up.
If you are thinking about selling this fall, price against today's rates, not last spring's, and expect to negotiate.
What the Fed Is Saying
On Thursday, Fed Governor Christopher Waller said more rate hikes are likely, but gave some room on timing: "The hikes do not need to come at consecutive meetings, but they should be in place in an acceptable period of time."
That matters to us because it keeps upward pressure on borrowing costs.
It is not a promise of lower rates any time soon.
What I'm Watching Next
Wednesday, October 14: the September inflation report (CPI), where a hot reading would likely push yields and mortgage rates higher.
Thursday, October 15: the next mortgage rate reading, to see whether the climb continues or pauses after seven straight increases.
Later this month: the September jobs data for Whatcom, to see whether August's jump was a blip or a trend.
Want to talk through what a 7.40% mortgage rate means for your plans to buy or sell in Whatcom County? Schedule a 15-minute call and we will go over your numbers.