The relief streak reached four straight weeks: the average 30-year fixed mortgage rate fell to 7.11%, its lowest level in seven weeks.
Four weeks of drops have now trimmed 0.29 points off the 7.40% plateau that held through mid-October.
The asterisk arrived Tuesday morning: October's inflation report came in hotter than expected, and bond yields climbed the rest of the week.
The 10-year Treasury yield ended Friday at 5.15%, up from 4.88% on Monday.
Locally there were no new numbers this week, so October's readings stand: 964 homes for sale and a $630,000 median list price in Whatcom County.
This Week's Numbers
These are the same numbers every Monday, so you can see the pattern build over time.
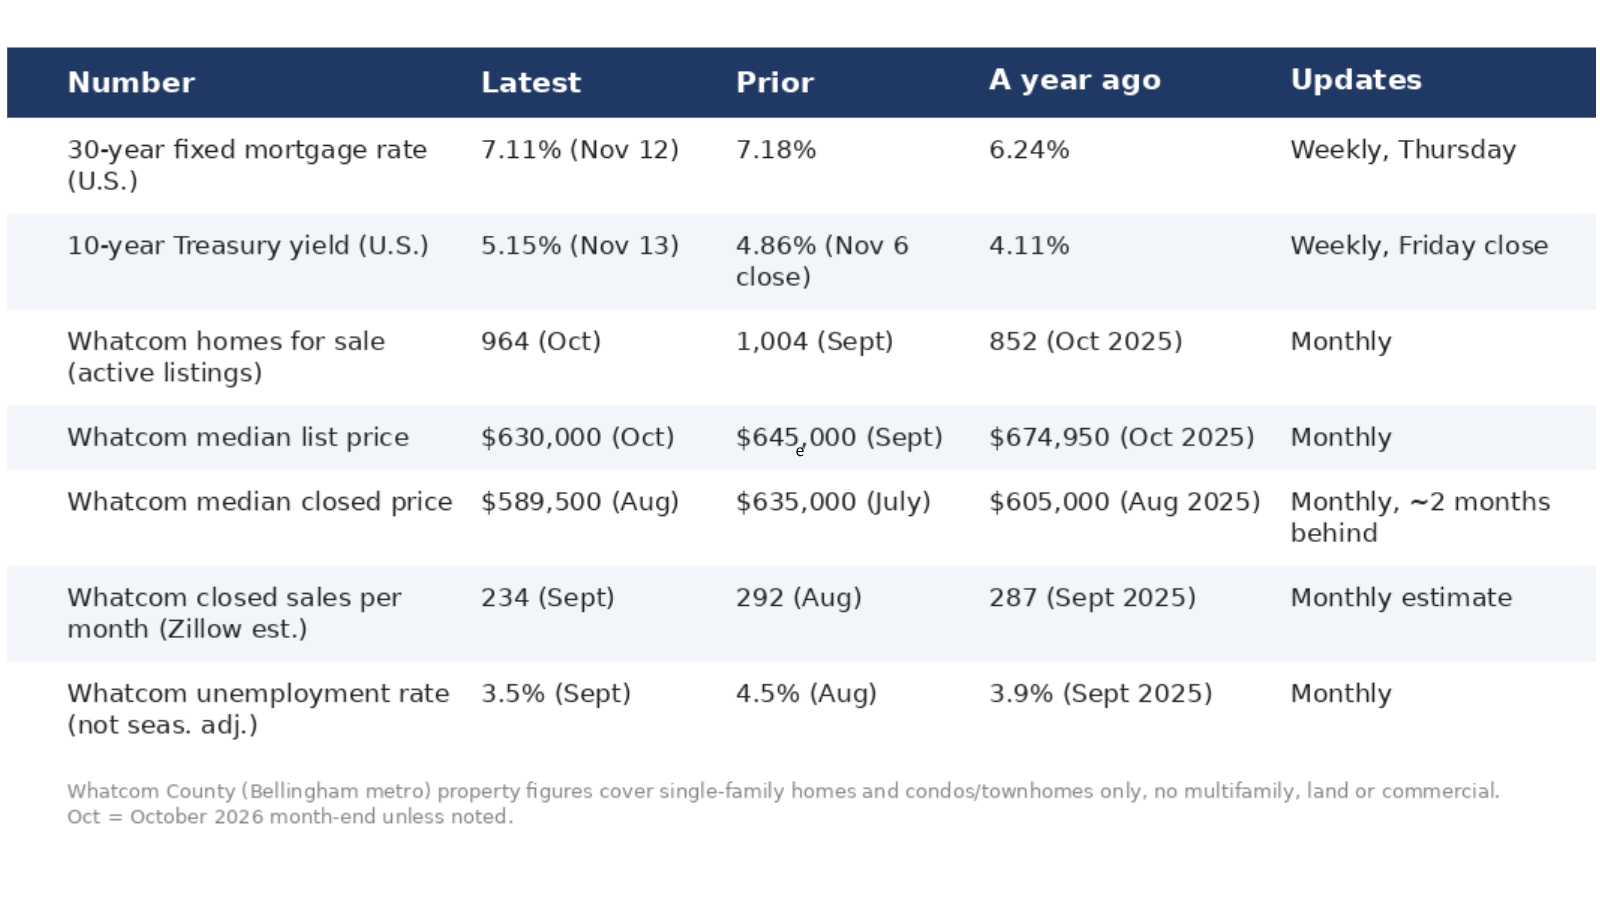
All property numbers cover single-family homes and condos/townhomes only (no multifamily, land or commercial).
Local numbers cover the Bellingham metro area, which is all of Whatcom County.
Listings and list price show what sellers are asking, and the two closed-sale rows show what homes actually sold for, with a lag.
What The Numbers Say
Rates.
A fourth straight weekly decline, down another 7 basis points to 7.11%, though most of the survey was collected before Tuesday's inflation report.
Yields.
The 10-year yield's weekly average rose after four straight weekly declines, from 4.89% to 5.03%, and Friday's 5.15% close was the week's high.
Inflation.
Consumer prices rose 0.4% in October, more than the 0.3% economists expected, and core prices rose 0.3% for a third straight month.
Inventory.
No new listings data this week: October's 964 active listings, down 4% from September's year-high 1,004, remain the latest reading.
List prices.
The median ask stands at $630,000, 6.7% below a year ago, with homes taking a median 64 days on market.
Closed sales.
Still no new closed readings, so August's $589,500 median closed price and September's estimated 234 sales stand for now.
How These Numbers Connect To Your Mortgage Rate
Mortgage lenders watch the 10-year Treasury yield when they price most fixed home loans, though it is not the direct benchmark for every loan.
Investors who buy mortgage bonds compare them to Treasuries, so when the 10-year yield moves, mortgage rates follow.
The result is a spread between mortgage rates and the 10-year yield, and that spread moves around over time.
This week that gap narrowed to about 2.08 points (a 7.11% mortgage rate versus a 5.03% weekly average yield), down from last week's 2.29.
That narrowing is mostly timing, since the mortgage survey predates the yield jump, which I read as a gap that widens back if yields stay high.
Over the last ten years that gap has averaged about 2 points, so both readings sit close to the usual range.
What This Means For Buyers
The math keeps moving in your direction, though this week comes with a caveat.
On a $645,000 home with 20% down, the monthly principal and interest payment is about $3,471 at 7.11%, roughly $24 less than the same quote a week ago.
Four weeks of drops have trimmed about $102 off the mid-October quote.
At last year's 6.24% the payment would be about $3,174, so the gap to a year ago is still roughly $297 a month for the same house.
If you are writing an offer soon, a fresh pre-approval shows your budget at today's lower quotes, and your lender can tell you when a rate lock becomes available, usually after an accepted offer.
What This Means For Sellers
Four straight weeks of rate relief are bringing buyers back into the pool, though Tuesday's inflation surprise may test that momentum.
October confirmed the seasonal turn: 964 homes for sale, down from September's 1,004, and a median asking price 6.7% below a year ago.
Well-priced homes still sell, but buyers are negotiating, and the 64-day median time on market says they are taking their time.
If you are thinking about selling before the holidays, price against today's rates and this month's inventory, not last spring's, and expect to negotiate.
What The Fed Is Saying
Freddie Mac's chief economist Sam Khater noted Thursday that mortgage rates "dropped to their lowest level in seven weeks, a welcome development that gives borrowers greater flexibility as they navigate the current housing market."
The Fed itself was quiet this week, but Tuesday's inflation report landed right in the middle of its debate.
Remember that the last meeting ended 10-2, with two members wanting to raise rates instead of holding.
A hotter inflation print gives those hawks fresh ammunition heading into the December 8-9 meeting, the last of the year.
What I'm Watching Next
Thursday, November 19: the next mortgage rate reading, the first to fully reflect the post-inflation jump in yields.
Late November: October's local unemployment reading, after September's encouraging drop back to 3.5%.
December 8-9: the Fed's last meeting of the year, where the hold-versus-hike debate gets decided.
December 10: the November inflation report, out the morning after the Fed's decision.
If you are thinking about a move this fall, schedule a 15-minute call and we can look at your numbers together.
Sources for reader review
Freddie Mac Primary Mortgage Market Survey (weekly 30-year rate) and the November 12 rate release with Sam Khater's comment
Washington Employment Security Department, Whatcom County profile (September unemployment)
Realtor.com Research, Whatcom County market data (listings and list prices)
Zillow Research data (closed sales and closed prices)
Property numbers cover single-family homes and condos/townhomes only.